
Home
Services
Blogs
Properties
About us
Who We Are
Contact us

View our Info Hub
UPDATED ON 25 FEBRUARY 2026
Under-Construction vs Ready-to-Move Property in Gurgaon: Which Should You Buy in 2026?
Book an under-construction flat and wait two or three years, or pay a premium to move in next month? The right answer depends less on the market and more on what kind of buyer you are.
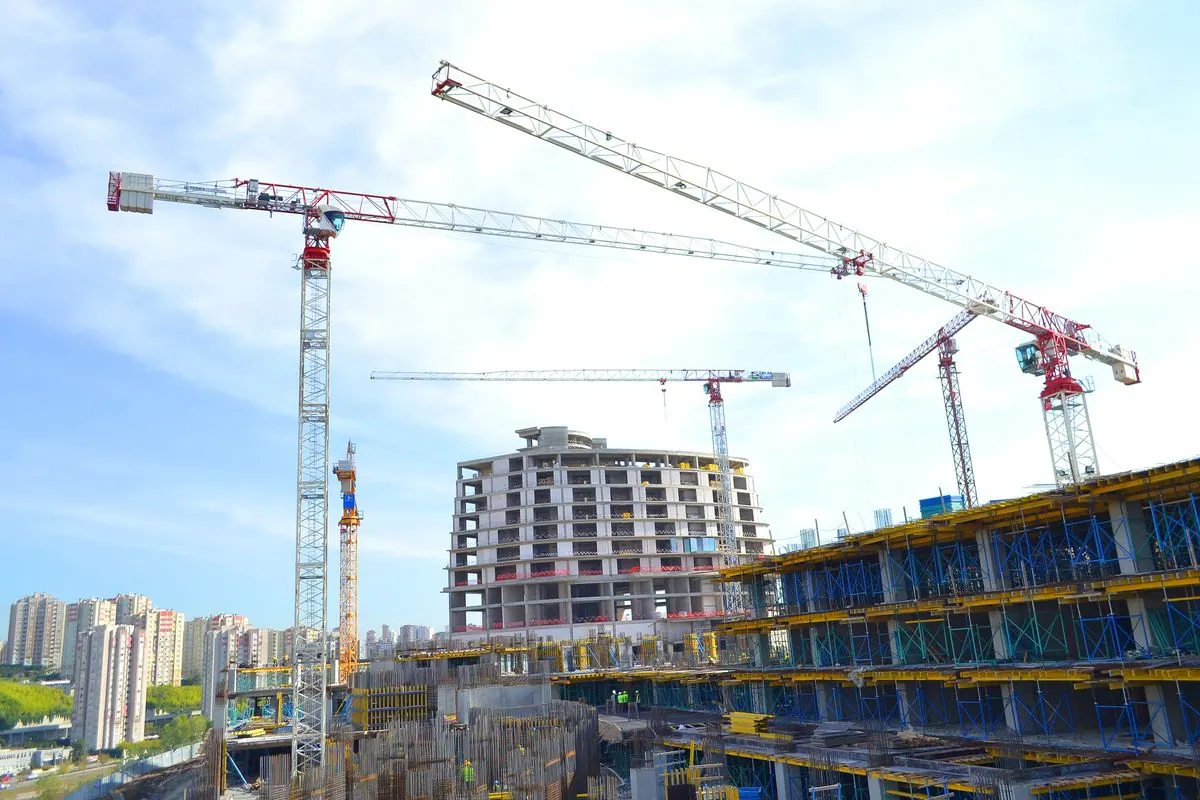
If you've started house-hunting in Gurgaon, you've already run into the question every buyer eventually faces: do you book an under-construction flat and wait two or three years, or pay a premium for something you can move into next month? Both paths are common in Gurgaon's market right now, from new launches along Dwarka Expressway to ready inventory in established sectors — and the right answer depends less on the market and more on what kind of buyer you are.
What "Under-Construction" and "Ready-to-Move" Actually Mean
An under-construction property is sold before the building is complete — sometimes before the foundation is even laid. You pay in installments tied to construction milestones, and possession happens on a promised (not guaranteed) date.
A ready-to-move property already has its Occupancy Certificate (OC), meaning construction is legally complete and you can get keys and move in almost immediately after registration.
Price Difference: Why Under-Construction Costs Less
Under-construction homes are typically priced 15–30% lower than comparable ready inventory in the same micro-market. Developers price this way because you're taking on construction-timeline risk that a ready-to-move seller has already absorbed. If you're buying purely for capital appreciation and can tolerate a multi-year wait, this gap is where the upside usually comes from.
GST: The Cost Most First-Time Buyers Miss
This is where many buyers get caught off guard:
- Under-construction property: attracts 5% GST on the base price (1% for affordable housing), with no input tax credit passed on to the buyer.
- Ready-to-move property with an OC: no GST applies at all, since the sale is treated as a transfer of immovable property, not a service.
On a ₹1.5 crore apartment, that 5% GST alone is ₹7.5 lakh — enough to meaningfully close the price gap between the two options once you run the actual numbers.
Risk and RERA Protection
Under-construction purchases carry two real risks: delivery delays and, in rarer cases, project stalls. RERA registration has made this far safer than it used to be — every registered project must deposit 70% of buyer funds in an escrow account earmarked for construction, and publish its promised completion date. Before booking any under-construction unit, check its RERA registration number on the Haryana RERA portal and look at the developer's track record on previous projects, not just the marketing brochure.
Ready-to-move property removes this risk entirely — what you see during your site visit is what you get.
Loan and EMI: Pre-EMI vs Full EMI
With a home loan on an under-construction property, banks disburse funds in tranches as construction progresses, and you pay pre-EMI (interest only) on the disbursed amount until possession — full EMI only starts once you get the keys. This keeps your monthly outgo lower during the wait, but means you're often paying rent and pre-EMI simultaneously if you need a place to live now.
With ready-to-move property, full EMI (principal + interest) starts immediately, but there's no parallel rent to budget for.
Rental Income and Immediate Use
If you're buying to rent out or live in immediately, ready-to-move wins by default — there's no 2–3 year gap where the property sits idle or half-built. If you're buying purely as a financial investment with a longer horizon, that gap doesn't cost you anything extra, since you weren't planning to occupy it anyway.
Quick Comparison
| Factor | Under-Construction | Ready-to-Move |
|---|---|---|
| Price | Lower (15–30% typical gap) | Higher |
| GST | 5% (1% affordable housing) | None |
| Possession | Promised date, not guaranteed | Immediate |
| EMI | Pre-EMI during construction | Full EMI from day one |
| Risk | Delay/stall risk (mitigated by RERA) | Minimal — what you see is what you get |
| Best for | Long-horizon investors, appreciation seekers | End-users needing immediate possession, risk-averse buyers |
So, Which Should You Buy?
There isn't a universally "right" answer — there's a right answer for your situation:
- Choose under-construction if: you have a 3–5 year horizon, don't need to move in immediately, and have verified the developer's RERA record and delivery history on past projects.
- Choose ready-to-move if: you need possession now, want to avoid GST and construction-delay risk entirely, or are buying your first home and prioritize certainty over price.
Whichever route you're leaning toward, run the numbers on GST, pre-EMI outgo, and realistic (not brochure) delivery timelines before you book.
Fynest Take
For most buyers today, ready-to-move is the safer default — no construction-delay risk, no GST, and certainty on when you'll actually move in. Under-construction only pulls ahead if you have a genuine 3–5 year horizon, don't need immediate possession, and have verified the developer's RERA record and delivery history. Run the real numbers — GST, pre-EMI outgo, realistic timelines — before you commit either way.
Trending Articles
View our Info Hub
Senior Living in India: Why It’s No Longer Just About Retirement
Oberoi Realty’s First Luxury Address in Gurugram: More Than Just Another Launch
Max Estate 360: A New Perspective on Luxury Living in Gurugram
Take the first step to financial
freedom and contact us today
Our team is ready to take you through every step of a successful property investment journey.
Make your move!

Join our
Community